Queen's University Algorithmic Network & Trading Team
Tomorrow's talent in quantitative finance, algorithmic trading, and data science.
Queen's students research, build, and trade quantitative strategies, learning and building side by side all year.
Explore Our ResearchRigorous Research. Real Portfolios.
Our members build live quantitative strategies across equities, rates, credit, options, and energy, and publish what they find.
- Portfolios this year
- 7
- Weeks of curriculum
- 10
- Papers published in 2025-2026
- 5
- Industry partners
- 5
Research, Written Up.
Every project team publishes a paper on the strategy it built. The 2025-2026 winner was Binomial Pricing.
Explore the Papers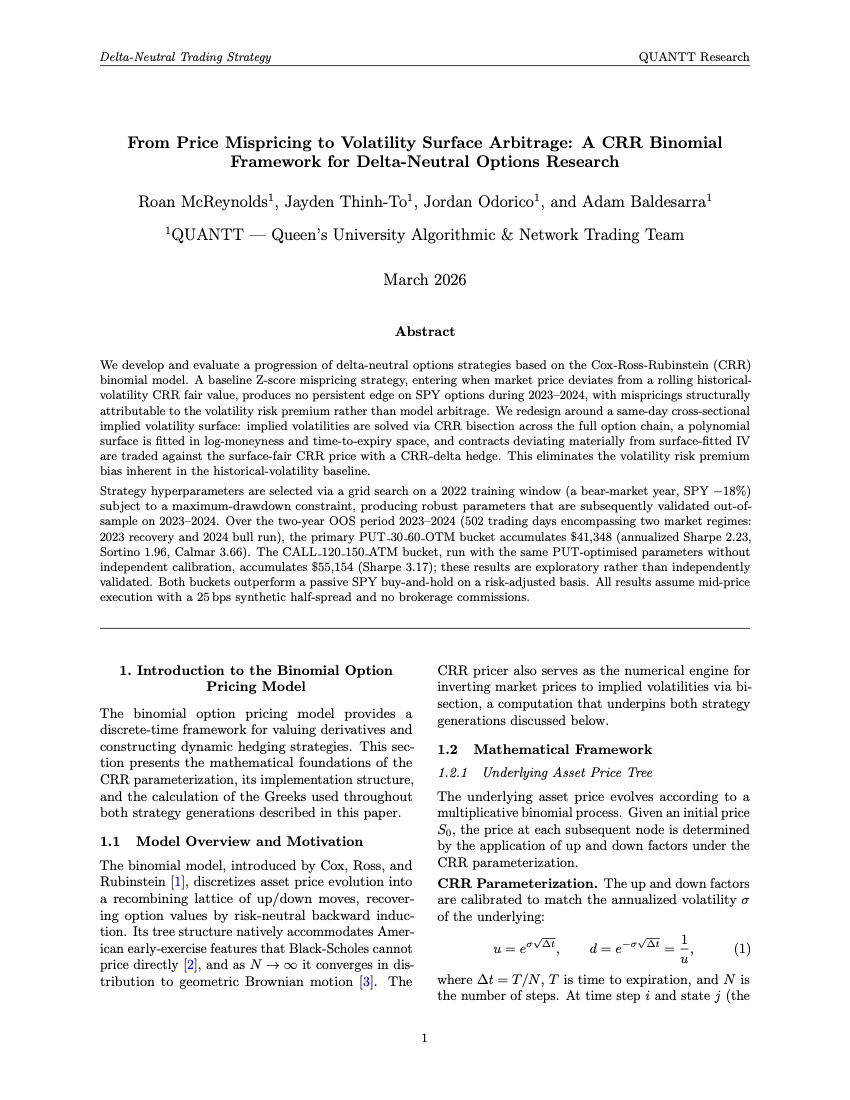
Learning and Building. All Year.
Members build their portfolio's strategy alongside the curriculum, so every lesson has somewhere to go. Two tracks: trading and development.
- Weeks of curriculum
- 10
- Tracks: trading and development
- 2
- Live portfolios
- 7
This Year's
Portfolios
7 desks for 2026–2027, each with its own thesis, data, and tooling.
Partner With QUANTT.
Ontario Teachers' Pension Plan, Picton Investments, National Bank of Canada, Connor, Clark & Lunn, QuantConnect work with QUANTT. We are looking for partners for the coming year.
Explore Partnerships